

How the Best Mutual Fund Company in Pune Sets Up an SWP
Key Takeaways
- Steady Cash Flow: An SWP lets you withdraw a fixed sum from your fund at regular intervals, like a planned paycheck.
- Tax on Gains: Each withdrawal has a cost part and a gain part, and tax applies only to the gain.
- Goal-First Planning: Exploring the best mutual fund investment plan in Pune, with distributors like Golden Mean Finserv, begins with knowing your monthly cash need.
- Market Risk Remains: Withdrawals continue even when markets fall, so your corpus can shrink faster than expected without regular reviews.
You’ve spent years building a corpus through SIPs.
Now a big question appears.
How do you turn that pile into regular monthly cash, without selling it all at once?
That’s the job of a Systematic Withdrawal Plan, or SWP.
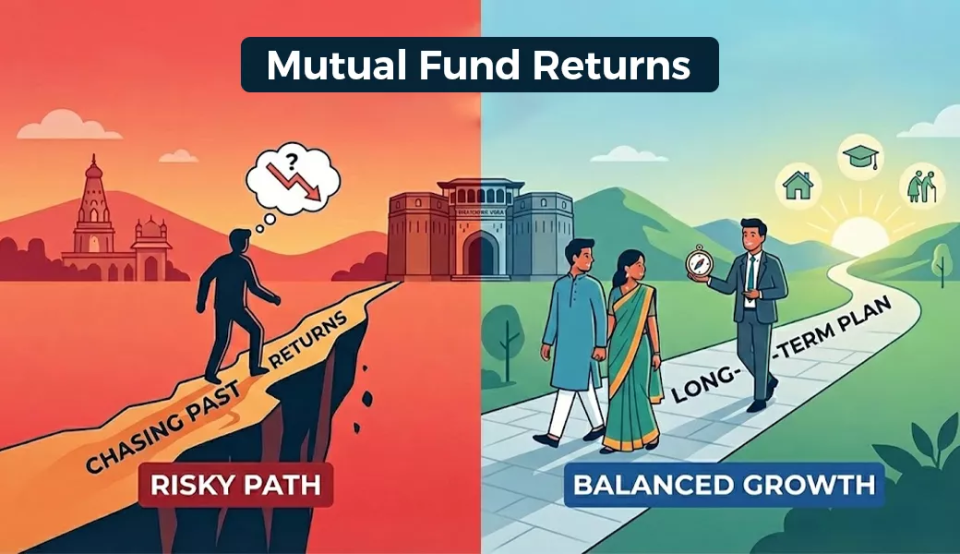
It sounds simple. But small choices, like the amount, the date, and the scheme, shape how it plays out.
So what does the best mutual fund company in Pune actually do to set one up for you? Let’s walk through it.
What an SWP Does to Your Corpus
An SWP is a SIP in reverse.
Instead of putting money in each month, you take money out.
On each chosen date, the fund house sells just enough units to pay your set amount.
The rest stays invested and keeps moving with the market.
When exploring the best mutual fund investment plan in Pune, distributors like Golden Mean Finserv explain this first: an SWP is a withdrawal tool, not a fund type.
It sits on top of a scheme you already hold.
Unlike IDCW payouts, which can vary, an SWP follows the amount and schedule you set.
How a Distributor Sets It Up
Here is the usual flow when an AMFI-registered distributor handles an SWP request:
- Understand your need
How much cash do you want each month, and for how long?
- Check KYC and folio details
PAN, bank account, and nominee should be current.
- Share scheme documents
The Scheme Information Document and factsheet show exit load, expense ratio, and risks.
- Fix the terms
You choose the amount, frequency, start date, and end date.
- Submit the instruction
It goes to the fund house or its registrar, along with your bank details.
- Track the first payouts
You confirm that credits match your instruction.
Notice who decides.
The distributor explains and processes. You make the call.
A reliable distributor also discloses commissions upfront, and regular plans cost more than direct plans.
How Much to Withdraw, and How Often?
Start with the monthly figure you actually need.
Here’s a hypothetical example.
Say your corpus is ₹50 lakh and you withdraw ₹30,000 a month.
That’s ₹3.6 lakh a year, or 7.2% of the corpus.
If the fund grows by less, the corpus shrinks. If it grows by more, the corpus can last longer.
Nobody can promise which one will happen.
Fixed Amount
You get the same sum every cycle, which makes budgeting easy.
Units sold change with the NAV.
Other Options
Some fund houses offer fixed units or gains-only withdrawals.
Monthly or quarterly schedules also vary, so check the scheme documents.
Tax and Exit Load on Each Payout
Every SWP payout is a redemption.
So each one can bring tax and, sometimes, an exit load.
Tax applies only to the gain part.
For equity-oriented funds, current rules (FY 2026-27) tax gains on units held over 12 months at 12.5%, above ₹1.25 lakh a year.
Shorter holdings attract 20%. Debt funds bought after 1 April 2023 are taxed at your slab rate.
Exit load is separate, and many schemes charge it on units sold within a set period.
A chartered accountant can explain how these rules apply to you.
When Markets Fall, Payouts Still Flow
An SWP pays on schedule, even when the NAV is low.
More units get sold to raise the same amount. Over time, that can drain your corpus faster than expected.
Keep these points in mind:
- Returns can be negative, and no payout is guaranteed.
- Withdrawing more than the fund grows eats into capital.
- Inflation can make a fixed payout buy less over time.
A yearly review helps. Most fund houses let you pause, change or stop an SWP on request
Conclusion
An SWP can turn a long-built corpus into steady cash flow.
It works best when you understand the mechanics first.
A distributor can explain the steps, share the documents, and handle the paperwork.
The choices stay yours.
Know your cash needs, check the tax and exit load, and review once a year.
FAQs
- Can I start an SWP in any mutual fund?
Most open-ended schemes offer SWP, but minimum amounts and options differ. The Scheme Information Document lists the details.
- Can I change or stop my SWP later?
A best mutual fund company in Pune, like Golden Mean Finserv, can submit your request to pause, change, or stop an SWP on your behalf. Processing timelines vary by fund house.
- Is the whole payout taxed?
No. Only the gain portion is taxed, and the rate depends on fund type and holding period.
- Is SWP income guaranteed?
No. Payouts depend on the units you hold and the NAV on the withdrawal date. Mutual fund schemes do not assure or guarantee returns.